Want to be in the loop?
subscribe to
our notification
Business News
FINANCIAL EMPOWERMENT FOR SMES
“The lack of transparency hardly creates confidence while credit is built on trust. Insufficient trust plus the lack of collaterals and an unfeasible business projects causes credit institutions to say 'No' to small and medium-sized enterprises (SMEs),” said Dr Vu Tien Loc, President of the Vietnam Chamber of Commerce and Industry (VCCI), at the Forum on Solutions to Boost Fund Sources for SMEs recently held by the Business Forum Newspaper in Hanoi.
Money still matters
Despite significant improvements in business environment in the last 30 years, money is still the biggest matter for SMEs in Vietnam, he said.
Vietnam is ranked 29th among 190 countries by credit access. In 2017, SMEs accounted for 21 per cent of total outstanding credit balance. Nevertheless, up to 60 per cent of SMEs have no access to capital sources. Among SMEs, startups do not have assets but business ideas and they need financial supports from the banking system to make money from their ideas.
The responsibility of making 60 per cent of SMEs inaccessible to credit sources is blamed to authorities (State Bank of Vietnam and relevant agencies), banks and SMEs themselves. The State lacks legal frameworks for creating financial channels for investors. State administration is still mechanical and risk-shy even in the time of the Industry 4.0. Land-use rights institutions impede enterprises from accessing bank loans,” Dr Loc said.
For banks and financial institutions, State-owned enterprises (SOEs) are still the priority of banks. Taking efficiency into account, banks prefer lending big sums to big corporates which can guarantee their borrowings with security assets. However, digital economy and start-up economy do not have many assets. Collateral-based loans still occupy a large share while performance-based lending has not become a mechanism or credit culture. How can we promote innovative start-ups?
On the enterprise side, Vietnam is home to about 670,000 enterprises, of which up to 98 - 99 per cent are SMEs. If over 5 million individual business units, micro and small enterprises according to economic concepts total nearly 6 million. So, almost all enterprises are small and micro. Among these nearly 6 million economic entities, only 2 million are registered, including 1.3 million individual entities and over 600,000 corporate entities. The rest is informally operational and typical of non-transparency. Even among 2 million registered entities, governance transparency is also a weakness for many.
Therefore, the lack of transparency hardly creates confidence while credit is built on trust. Insufficient trust plus the lack of collaterals and an unfeasible business projects causes credit institutions to say “No” to SMEs, said Dr Loc.
New loan methods needed
To open up capital flows for SMEs, the responsibility belongs to authorities, banks and SMEs together. On the one hand, institutions and bottlenecks in operation of financial entities and businesses need to be solved at the same time. To do this, it is necessary to deal with above issues. For its part, the State needs to more strongly reform policies and legal frameworks, facilitate lending in the era of Industry 4.0, and stimulate innovative start-ups. At the same time, it needs to have policies to strengthen interaction between enterprises and financial institutions.
He said, banks should make a greater effort to introduce new lending methods, direct funds for innovative start-ups and farmers based on their business ideas and plans. Credit and financial institutions and insurance companies need to interact to cover each other in supporting SMEs, promote credit-based microfinancing and apply information technology to reduce procedures.
At the same time, lending is suggested to base on supply chains. For example, loans are decided by crops, livestock or fields owned by borrowing farmers, or based on business plans rather than factories because these facilities are hardly available in agricultural production.
Investment is not risk free, said Dr Loc. This requires efforts of the banking system. Banks not only lend enterprises but the former also advise and support the latter. Banks have the advantage of connecting and leading partners for target enterprises in business investment. If both banks and enterprises interact, open up capital sources, create development motivations and reduce risks for both sides.
To fundamentally change this symbiotic relationship, enterprises need to be transparent and banks must raise their levels to have better interrelationship.
SMEs must ensure transparency. In the era of international integration and Industry 4.0, transparency is the most important in addition to enhancing governance. Vietnam is ranked among the 20 most entrepreneurial economies in the world and it is also among 20 economies capable of realising lowest start-up ideas. As a result, SMEs need to improve their governance capacity, which is aligned with transparency as the first important benchmark in accessing bank loans and financial institutions.
Mr Nguyen Quoc Hung, Director of the Credit Department, SBV
By consistently carrying out supporting measures, enabling SMEs to access credits for business development, and growing outstanding credit for SMEs in the past years and in the first half of 2018, credits for SMEs produced certain results. As of June 30, 2018, outstanding loans to SMEs nationwide reached VND1,402.89 trillion (US$60 billion), up 4.48 per cent from the end of 2017 and equal to about 21 per cent of total outstanding loans of the economy.
Credits for SMEs have steadily increased in recent years and basically met financial demands of SMEs qualified for borrowing at banks. According to the State Bank of Vietnam, over 270,000 SMEs have outstanding loans at credit institutions.
To facilitate SMEs to access capital sources, authorities should soon complete legal documents (decrees and circulars) guiding the Law on SME support, ensure that SME support policies are enforced in concert and effectively. Provincial/Municipal People’s Committees should actively apply SME support regulations specified in the Law on SME Support and guidance from central authorities and closely work with banks to implement bank - business connection programmes in order to jointly solve difficulties in land, tax and infrastructure when enterprises access loans for business development.
Particularly, business associations should enhance their role and influence to act as bridges for SMEs to approach credit institutions, provide SMEs with market information, trade promotions and exhibitions and protect legitimate rights and interests of their members.
Finally, SMEs must also self-perfect, comply with laws and actively provide full and honest information to enhance their prestige to credit institutions, join manufacturing activities along value chains, and allow credit institutions to control their cash flows and financial situations during the borrowing term.
Dr Can Van Luc, Economist
Some credit institutions lack interest in SME customers, partly due to low profit margin (caused by upper-limit lending interest rates) while risks and operating costs are high. In addition, ineffective coordination between the SME Credit Guarantee Fund and credit institutions (in appraisal, collateral receipt, obligation guarantee, risk treatment) is another cause.
In SME funding forms, attention should be paid to their unfamiliar forms like share issue, bonds issue and financial lending. Accordingly, it is necessary to effectively issue and execute legal documents guiding the enforcement of the Law on SME Support while strengthening the role of SME associations and cooperation between credit institutions and credit guarantee funds.
The Government, the Ministry of Finance, the State Bank of Vietnam and related business associations effectively and consistently carry out the Law on SME Support and other support policies (supporting industries, agriculture and rural development); and strengthen the operation of the SME Guarantee Fund in collaboration with credit institutions, associations, local authorities and SME development funds. In particular, consideration should be given to the mechanism of capping lending rates for SMEs, building market and product information systems, SME support partners and developing business information systems.
Financial institutions necessarily design specific credit products and processes tailored for SMEs; develop credit supply chains and cooperate with large enterprises to finance SMEs; enhance cooperation effectiveness, coordinate with funds, especially the Credit Guarantee Fund and SME Development Fund, to share information and connect enterprises.
Dr Nguyen Thi Hien, Deputy Director of Banking Strategy Institute, SBV
There are two existing issues that impede SMEs from accessing capital. Firstly, SME performance is not high and the share of loss-making SMEs is higher than that of larger firms.
Secondly, they are weak at information governance, reporting system, and information transparency. Therefore, the time needed to appraise borrowing requests is longer.
For banks, credit products are worthy. In addition, many organisations have applied the same credit granting and credit scoring processes. Therefore, they should change their views on risk tolerance of SMEs.
Notably, with the current diverse structure, Vietnamese credit institutions can provide credit to more borrowers. As a result, more SMEs can access bank loans.
Enterprises need to clarify information, improve operating quality, enhance management capacity, and have good business plans to have an easier access to credit sources. Banks should make an effort to develop appropriate products, improve credit scoring methods, and have appropriate credit packages for each target group.
Source: VCCI
Related News
MEMBER CORNER / PROMOTIONS
THE REVERIE SAIGON CELEBRATES THE FESTIVE SEASON WITH CURATED CULINARY EXPERIENCES AND BESPOKE CELEBRATIONS
Ho Chi Minh City, Vietnam, 12 November 2026 – The Reverie Saigon, a member of “The Leading Hotels of the World”, unveils its 2026 festive program, presenting a wide range of holiday offerings across its dining venues, spa, and accommodations. Reflecting Ho Chi Minh City’s growing reputation as a leading dining destination, this year’s festive offerings bring together diverse culinary experiences
MEMBER CORNER / PROMOTIONS
PASTA WEEK: EMBARK ON A FLAVOURSOME CULINARY VOYAGE AT NOI
From November 9 to 22, 2026, NOI restaurant located on Level 3 of the Union Square - presents Pasta Week, an exclusive culinary journey celebrating the spirit of "A Celebration of Us". Taking inspiration from its name "NOI", which means "Us" in Italian, the specially curated menu unfolds like a vessel bearing warmth and brings people closer around the dining table.
VIETNAM ECONOMY INVESTMENT
AVERAGE STARTUP CAPITAL PER NEW BUSINESS DOUBLED TO $800,000
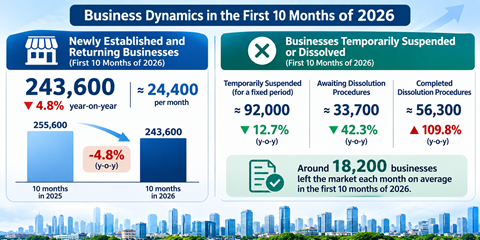
More than 243,600 businesses were newly established or resumed operations in the first 10 months of 2026, averaging 24,400 a month, according to the National Statistics Office under the Ministry of Finance. Total additional registered capital reached nearly VND5.8 quadrillion ($227 billion), up 11.6 per cent on-year.
VIETNAM ECONOMY INVESTMENT
VIỆT NAM SEEKS NEW GROWTH DRIVERS TO ACHIEVE DOUBLE-DIGIT EXPANSION IN 2027
The target, approved by the National Assembly (NA) on November 7, comes amid encouraging economic performance in the first 10 months of 2026. However, sustaining high growth will require more than increased investment and credit. Improving productivity, strengthening the private sector, promoting industrial development and accelerating science and technology adoption will be crucial to turning the ambitious target into reality.
VIETNAM ECONOMY INVESTMENT
VIETNAM’S TRADE TURNOVER SURPASSES $1 TRILLION FOR THE FIRST TIME
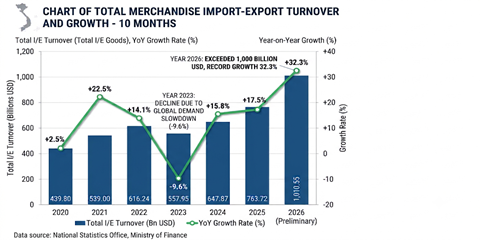
Total merchandise trade reached more than $1 trillion in the first 10 months of 2026, up 32.3 per cent on-year, according to the National Statistics Office under the Ministry of Finance. Exports hit $499.24 billion, up 27.5 per cent, while imports totalled $511.3 billion, up 37.4 per cent. With imports outpacing exports, Vietnam posted a merchandise trade deficit of $12.07 billion, compared with a surplus of about $19.5 billion a year earlier.
INFRASTRUCTURE / CONSTRUCTION / LOGISTIC / PORT
VIỆT NAM TO DEVELOP A NATIONAL PROGRAMME TO BOOST MARITIME INDUSTRY
Việt Nam will develop a national programme for the maritime and marine engineering industries through 2035 as part of the effort to strengthen domestic industrial capacity and build a modern, competitive and self-reliant maritime industry. Under Decision 2089/QĐ-TTg, signed by Permanent Deputy Prime Minister Phạm Gia Túc, the Government seeks to address existing difficulties and bottlenecks, mobilise resources and make more effective use of the industry's existing capabilities.
Events Sponsors