Want to be in the loop?
subscribe to
our notification
Business News
POSITIVE OUTLOOK FOR BANKING INDUSTRY
The “black shadow” of the pandemic has receded, giving way to a bright picture of the banking industry in the last six months of 2022.
According to a survey recently released by Vietnam Report Joint Stock Company, 63.6% of respondents anticipated higher growth in the banking industry than last year, slightly higher than last year's respondents (58.8%). About 9.1% of respondents are cautious about the banking outlook. This figure is considered very positive as compared to the time when the COVID-19 pandemic spread and cast a shadow over most economies, making 76.9% worried about slowing growth (June 2020).
Strong credit recovery
Bright colors on the banking outlook are dominant with strong credit growth recovery. Credit growth in 2021 returned to the pre-pandemic level (in 2019), reaching 13.6%. Credit grew nearly 8.2% in the year to June 9, 2022 and 17.1% from a year earlier. Most respondents forecast a credit growth of over 14% in 2022, mainly driven by retail lending. Consumer lending in Vietnam remains quite modest relative to other countries in the region, which shows huge room for growth.
Besides, deposits have rebounded, and been anchored with low-interest rates. Alternative investment channels and a decline in personal income put pressure on deposit growth in 2020-2021. However, the interest rate race started to heat up about three months ago. As of early June 2022, deposit rates increased significantly, with 10 banks offering above 7% per annum. The increase in deposit interest rate has drawn unemployed money into banks again. The survey by Vietnam Report showed that 81.8% believed deposits to grow strongly in 2022.
Notably, non-interest income grew well, mainly from bancassurance. 100% of respondents said that interest income will be more difficult in the coming time because of increasingly strict risk management policies. Therefore, non-interest income will become a driving force of profit. Among non-interest incomes, fee and commission income has grown steadily with a compound growth rate of 28.3% in the 2018-2021 period (according to FiinReasearch). Two main contributors to this growth are bancassurance revenue and card service fee. Statistics show that the bancassurance fee contributed about 31% to the total fee and commission income of banks in 2021. Therefore, non-interest income was expected to keep growing in the short and medium terms. In addition, the source of income from the recovery of written-off bad debts may be an extraordinary source of income for the banking industry in the near future.
Potential risks
In the banking picture, besides bright colors, "gray areas" have also begun to appear more clearly in asset quality as the hiatus of COVID-19 impacts has gradually shortened.
The first is the cross-default risk of real estate bonds. As credit has been tightened since late 2019, bond issuance has become an effective approach for real estate firms to raise funds for their projects. According to the Vietnam Bond Market Association (VBMA), bond issues rose about 18.98% year on year to VND56,674 billion in the first quarter of 2022, of which VND28,581 billion came from real estate firms. However, property bonds are presently facing difficulty following a series of legal violation cases. According to FiinResearch, repayment pressures on bond maturity are huge for real estate businesses within the next three years. This can cause liquidity risk of distribution agents committed to buying back bonds, especially banks. Half of the corporate bonds that banks are holding are real estate bonds. Therefore, banks may face the risk of cross-default because a large amount of real estate bonds of unlisted enterprises is classified into doubtful debt groups.
In particular, the increase in bad debts has potentially posed risks to system safety. According to statistics, bad debt tends to climb quite strongly. Pandemic impacts on banks' balance sheets are expected to extend when businesses are unable to get recovered and unimproved debts, after being restructured to stay in Debt Category 1 and Debt Category 2, will force the banking system to officially record them as non performing debt, especially after Circular 14 expires on June 30, 2022. Due to the prospect of increasing bad debts in 2022, since the end of last year, most banks have raised their hedging ratio to help improve their asset quality and profit “provision” for this year.
This trend is extending as Vietnam Report's survey showed that 45.5% of banks expect to further hedge risks, 36.4% to keep the same risk provisions as last year and only 18.2% to reduce risk provisions. However, lower risk provisioning growth than bad debt growth caused the average provisioning coverage ratio for bad debts to decrease slightly from 118% at the beginning of the year to 112% at the end of the first quarter of 2022. The announced bad debt coverage ratio is likely to pick up in the second half of 2022, after Circular 14 expires. Accordingly, increasing hedging resources to handle bad debts at banks has become more urgent than ever.
In the context of deepening development and integration, the banking sector needs to implement higher international standards such as Basel II and Basel III in order to improve risk management capacity and enhance competitiveness with other banks. One important risk management indicator is the capital adequacy ratio (CAR). According to FiinResearch, CAR of Vietnamese banks was only 11.3% in 2021, quite low relative to other countries in the region, while it showed signs of decline in the first quarter of 2022. Large state-owned banks could hardly meet Basel II capital adequacy requirements. The decline in CAR is partly because credit institutions are applying Circular 41/2016/TT-NHNN toward Basel II, with stricter requirements for calculating risk assets and imposing a higher credit risk coefficient on securities and property loans. Although the registered capital of banks increased a lot in 2021 by issuing dividend stocks, it is observed that the growth has shown signs of slowing down. In the current volatile economic and credit risk environment, capital increase pressures are weighing heavily on banks, becoming one of the biggest challenges to growth this year to 36.4% of banks, an increase of 8.6% over last year (according to a survey by Vietnam Report). More than 54.6% of banks said that increasing the registered capital is a key task in 2022, significantly higher than 44.4% in the previous year.
The 2022 banking outlook depends greatly on how the COVID-19 pandemic is controlled and well as how the economy recovers. If economic recovery is fast enough, the capital absorption capacity of the economy will be increased, the capital supply of the banking system will be enhanced, asset quality and income of banks will be improved. Growth figures in agriculture, industry, trade, tourism, and services in the first months of the year show that Vietnam's economy is thriving, with the second-quarter GDP growth estimated at 7.72%, higher than all second quarters of 2011-2021 period. The GDP expanded 6.42% in the first six months of 2022, higher than the growth of 2.04% in the same period of 2020. This is really a positive signal for the banking industry to develop safely and firmly in the coming time.
Source: VCCI
Related News
MEMBER CORNER / PROMOTIONS
THE REVERIE SAIGON CELEBRATES THE FESTIVE SEASON WITH CURATED CULINARY EXPERIENCES AND BESPOKE CELEBRATIONS
Ho Chi Minh City, Vietnam, 12 November 2026 – The Reverie Saigon, a member of “The Leading Hotels of the World”, unveils its 2026 festive program, presenting a wide range of holiday offerings across its dining venues, spa, and accommodations. Reflecting Ho Chi Minh City’s growing reputation as a leading dining destination, this year’s festive offerings bring together diverse culinary experiences
MEMBER CORNER / PROMOTIONS
PASTA WEEK: EMBARK ON A FLAVOURSOME CULINARY VOYAGE AT NOI
From November 9 to 22, 2026, NOI restaurant located on Level 3 of the Union Square - presents Pasta Week, an exclusive culinary journey celebrating the spirit of "A Celebration of Us". Taking inspiration from its name "NOI", which means "Us" in Italian, the specially curated menu unfolds like a vessel bearing warmth and brings people closer around the dining table.
VIETNAM ECONOMY INVESTMENT
AVERAGE STARTUP CAPITAL PER NEW BUSINESS DOUBLED TO $800,000
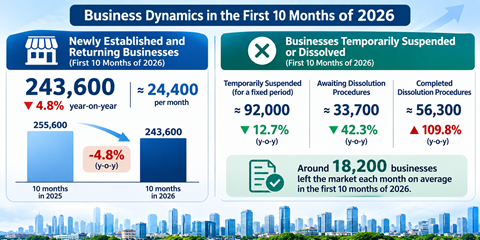
More than 243,600 businesses were newly established or resumed operations in the first 10 months of 2026, averaging 24,400 a month, according to the National Statistics Office under the Ministry of Finance. Total additional registered capital reached nearly VND5.8 quadrillion ($227 billion), up 11.6 per cent on-year.
VIETNAM ECONOMY INVESTMENT
VIỆT NAM SEEKS NEW GROWTH DRIVERS TO ACHIEVE DOUBLE-DIGIT EXPANSION IN 2027
The target, approved by the National Assembly (NA) on November 7, comes amid encouraging economic performance in the first 10 months of 2026. However, sustaining high growth will require more than increased investment and credit. Improving productivity, strengthening the private sector, promoting industrial development and accelerating science and technology adoption will be crucial to turning the ambitious target into reality.
VIETNAM ECONOMY INVESTMENT
VIETNAM’S TRADE TURNOVER SURPASSES $1 TRILLION FOR THE FIRST TIME
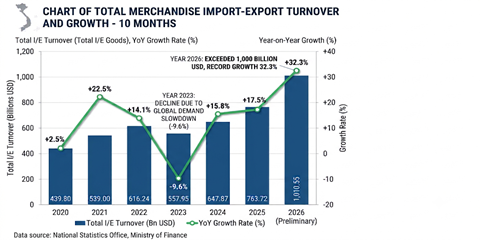
Total merchandise trade reached more than $1 trillion in the first 10 months of 2026, up 32.3 per cent on-year, according to the National Statistics Office under the Ministry of Finance. Exports hit $499.24 billion, up 27.5 per cent, while imports totalled $511.3 billion, up 37.4 per cent. With imports outpacing exports, Vietnam posted a merchandise trade deficit of $12.07 billion, compared with a surplus of about $19.5 billion a year earlier.
INFRASTRUCTURE / CONSTRUCTION / LOGISTIC / PORT
VIỆT NAM TO DEVELOP A NATIONAL PROGRAMME TO BOOST MARITIME INDUSTRY
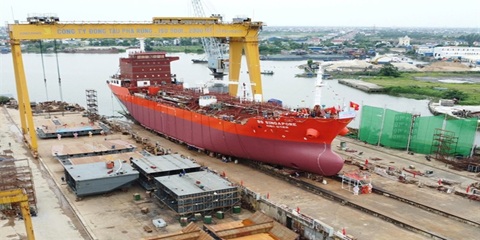
Việt Nam will develop a national programme for the maritime and marine engineering industries through 2035 as part of the effort to strengthen domestic industrial capacity and build a modern, competitive and self-reliant maritime industry. Under Decision 2089/QĐ-TTg, signed by Permanent Deputy Prime Minister Phạm Gia Túc, the Government seeks to address existing difficulties and bottlenecks, mobilise resources and make more effective use of the industry's existing capabilities.
Events Sponsors