Want to be in the loop?
subscribe to
our notification
Business News
SUSTAINING FINANCIAL RESOURCES
Currently, the financial market in Vietnam has been basically formed and has played a particularly important role in mobilizing savings and allocating capital sources. The financial market has also made remarkable progress in nature and scale to fuel the economy, support business growth and effectively facilitate economic restructuring. However, the development of Vietnam's financial market is not commensurate with its potential, and has yet to integrate deeply into the international market with many new technology applications.
Financial resources are key to economic activities. Financial capital (e.g. stocks, bonds or banknotes) is important to enable other types of capital to be owned and worked. It however has no real value in itself but only represents natural, human, social or productive capital. Financial capital includes two types: domestic capital (state budget, state credit for development investment, investment capital of SOEs and private capital) and foreign capital (FDI, ODA and credit capital from international commercial banks and international capital markets).
Sustaining Financial Resources
Currently, the financial market in Vietnam has been basically formed and has played a particularly important role in mobilizing savings and allocating capital sources. The financial market has also made remarkable progress in nature and scale to fuel the economy, support business growth and effectively facilitate economic restructuring. However, the development of Vietnam's financial market is not commensurate with its potential, and has yet to integrate deeply into the international market with many new technology applications.
Financial resources are key to economic activities. Financial capital (e.g. stocks, bonds or banknotes) is important to enable other types of capital to be owned and worked. It however has no real value in itself but only represents natural, human, social or productive capital. Financial capital includes two types: domestic capital (state budget, state credit for development investment, investment capital of SOEs and private capital) and foreign capital (FDI, ODA and credit capital from international commercial banks and international capital markets).
In Vietnam, the average demand for total social investment funds in the period of 2021-2025 is about 32-34% of GDP; meanwhile, the public investment capital in these five years is just 16-17% of total social investment capital. In addition, businesses are currently short of capital flow. Research results show that up to 50% of surveyed enterprises said they faced difficulty in accessing capital. To deal with the capital shortage, 4% of enterprises had to seek informal credit sources.
The financial strategy for 2030 defines the following objectives: Building a sustainable and modern national financial system and building policies for mobilization, allocation and effective use of financial resources to realize tasks stated in the 10-year Socioeconomic Development Strategy for 2021-2030 which emphasizes the need for synchronous, transparent and sustainable development of financial markets and financial services.
Currently, the financial market in Vietnam has been basically formed and has played a particularly important role in mobilizing savings and allocating capital sources. The financial market has also made remarkable progress in nature and scale to provide funds for the economy, support business growth and effectively facilitate economic restructuring. All three markets - banking, securities and insurance, financial products and services have been developed rapidly with many new products and services introduced to meet the increasing and diverse needs of customer segments. Statistical data show that Vietnam's capital market grew at an average of 28.5% a year in the 2016-2021 period. By the end of the first quarter of 2022, the capital market equaled 134.57% of GDP in 2021, up to 3.5 times its size in 2015. Particularly, the stock market capitalization equaled 93.8% of GDP and the bond market capitalization reached 40.7% of GDP, of which government bonds took 22.7% and corporate bonds made up 16.4%.
Shortcomings
However, the development of Vietnam's financial market is not commensurate with its potential, and has yet to integrate deeply into the international market with many new technology applications. The financial market with highly liquid products satisfies the short-term regular needs of people. As an inherent human characteristic - "greed without limits" (Book "Building a socialist rule of law state of the people, by the people and for the people" according to Ho Chi Minh's thought – Su That National Politics Publishing House, December 2021), this market also carries many potential risks (such as gambling, money laundering, property appropriation, market manipulation, insider trading, insurance fraud, corruption and cheating). We can raise four specific shortcomings as follows:
Pricing products and services: The relationship between the real estate sector and the financial sector is very close and organic. Creating a real estate price index is essential because real estate prices are used as one indicator of financial system stability and play an important role in making monetary decisions.
The current economy has a two-price land mechanism. A land price framework is fixed by the government. Another agreed by economic sectors in the market is called the market price. The growing gap between the two prices is resulting in greater social injustices and is blamed for unharmonized interests of the government, people and businesses and for distortion of the real estate market that may give rise to potential risks to the whole economy. In addition to this shortcoming, given that Vietnamese accounting standards are still different from and inconsistent with international accounting standards, some entities will exploit existing loopholes to make incorrect transaction accounting.
In the banking market, the settlement of bad debts at credit institutions is facing many unresolved difficulties, mainly relating to collateral handling. This matter is becoming more and more serious when some businesses are increasingly reliant on credit loans, using non-transparent and non-market forms or issuing fraudulent stocks and bonds instead of raising equity capital.
Like many other developing countries, despite high growth rates, we are lagging behind in life quality in both urban and rural areas. Unemployment, housing shortage, poor health and environmental quality, crime, poverty, traffic congestion and other problems are troubling both urban residents and authorities at all levels. An unprofessional credit system coupled with unrealistically strict requirements for loans has left SMEs, MSMEs and especially low-income households excluded from the credit supply network in a systematic manner by commercial banks. Many surveys show that banks require borrowers to be employed in the formal sector, with an acceptable income, while a majority of surveyed households are engaged in the informal or temporary sector at construction sites and in industrial zones. Thus, their incomes are irregular and uncertain. Banks require that only borrowers with valid land ownership are eligible for loans, but most low-income households are living in rented houses and do not own land. They own very few assets and their savings are not enough to act as collateral. The lack of access to bank loans has led SMEs, MSMEs and households to shift to the informal credit market or black credit to meet their needs.
The incommensurate size of the financial market is putting a brake on its development and international integration in the context of strong growth in digital finance, shared finance and green finance. By the end of 2020, total assets of Vietnamese financial institutions equaled 219% of the country’s GDP, lower than average 320% of GDP of the Top 5 ASEAN countries. Stock market capitalization was about 84% of GDP, lower than that in regional markets (ranging from 93% to 243%, except for Indonesia). Outstanding debt in the bond market reached 44.7% of GDP, quite small relative to other markets in the region. Notably, outstanding loans in the corporate bond market equaled 14.5% of GDP, only about half the average of Asian corporate bond markets (25.8%).
The Document of the 13th Congress clearly states: The Government administers the economy by law, mechanisms, policies, strategies, master plans, detailed plans, standards and norms in accordance with market economic requirements and laws. The market plays a decisive role in pricing goods and services; effectively enables motivations and allocations of resources; regulates production and circulation; and governs business operations to get rid of weak enterprises.
Recommendations
Building a consistent institution for the financial market to price financial assets on an open and transparent market mechanism. The financial market must make objective and accurate valuations to ensure liquidity for all other resources such as productive capital, human, social and natural resources in order to mobilize total capital resources for socioeconomic development. In the near term, the upcoming amendment to the Land Law is necessary to have a unified land price policy to ensure fairness and sustainable socioeconomic development.
Supervision needs to be effectively enhanced with three key contents: Monitoring systemic risks; strengthening coordination between policy-making agencies and supervisory agencies; and coordinating, and synchronizing macro and micro-prudential supervision. In addition, inspection quality has been raised with gradually established market disciplines, regulatory enforcement and increased sanctions for violations on the financial market (money laundering, property appropriation, market manipulation, insider trading and insurance fraud). The system of credit institutions needs to be restructured with a focus on fundamental and thorough settlement of bad debts and weak credit institutions, using suitable market-based forms on the principle of prudence, guaranteed interests of depositors and continued system stability and safety.
The informal credit market (including black credit) is an objective reality in the financial market. The question is: Why do SMEs, MSMEs and particularly low-income households use informal credit for their investment needs? Is it because they are not eligible for formal credit? Or is it because informal credit is a viable option given their socioeconomic status and location? Or is it a combination of both? Awareness and insightful research of micro-credit financial policymakers on the above issues will help find an intermediary ground for a more comprehensive capital channel to use and help build a sustainable society.
Today, given the current pace of global liberalization, markets cannot develop separately but they must be interconnected. There will be some global development trends for the financial market in the coming time which will affect the financial market of each country. This requires development orientations for the financial market and the business community in 2021-2030 towards sustainability, healthy competition and modernity. This will build a reasonable structure for the monetary market, the capital market and the domestic insurance market to gradually connect with the international financial market, ensure mobilization of domestic and international financial resources for strategic breakthroughs, economic restructuring, new growth patterns, increased productivity, performance and competitiveness of the economy.
Source: VCCI
Related News
CHARITY / EXHIBITION / OTHER EVENTS
INVESTMENT OPPORTUNITIES IN CA MAU PROVINCE: 96 PROJECTS AND 20 STRATEGIC PROJECTS
We are pleased to share with you information on investment projects currently seeking investors in Ca Mau Province. Should your esteemed company or association be interested, we kindly invite you to review the project information and complete the registration form via the links provided. The Ho Chi Minh City Investment and Trade Promotion Centre (ITPC) will consolidate the expressions of interest and facilitate connections with the leadership of Ca Mau Province at a meeting tentatively scheduled for 13 November 2026 in Ho Chi Minh City.
MEMBER CORNER / PROMOTIONS
BẰNG KIỀU LIVESHOW - A SYMPHONY OF LOVE UNDER THE GOLDEN GLOW
A masterclass in live music that takes the audience on a soulful journey through immortal love songs, guided by the peerless artistry and emotive storytelling of renowned singer Bằng Kiều. The highlight of the night is his seamless musical chemistry with special guest Triệu Hồng Ngọc, promising passionate and deeply resonant duets inside the magnificent Grand Ballroom.
INFRASTRUCTURE / CONSTRUCTION / LOGISTIC / PORT
ĐÀ NẴNG GREEN-LIGHTS US$105 MILLION THAI DEVELOPMENT DEAL
The central city has approved an investment proposal by Thailand’s WHA Group to develop infrastructure for the 400ha WHA Đà Nẵng Industrial Park project on two communes of Thăng Bình and Đồng Dương, with an investment of more than VNĐ2.7 trillion (US$105 million). The city said it approved WHA Industrial Development International's status as an investor in the project, which is expected to take place between 2027 and 2034.
VIETNAM ECONOMY INVESTMENT
MOBILE PHONE EXPORTS RISE 20% TO $51.8 BILLION IN FIRST NINE MONTHS
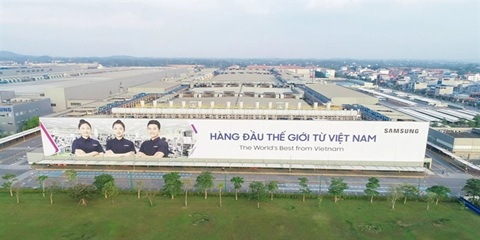
Exports of mobile phones and components rose 20 per cent year-on-year to nearly US$51.8 billion in the first nine months of 2026, with China, the US and Republic of Korea accounting for more than half of the total. Shipments to the three markets reached a combined $26.18 billion, or 50.6 per cent of total exports of the product group during the period, according to data from the Vietnam Department of Customs under the Ministry of Finance.
INFRASTRUCTURE / CONSTRUCTION / LOGISTIC / PORT
VIỆT NAM-CAMBODIA TRADE GATHERS PACE TOWARDS $20 BILLION TARGET
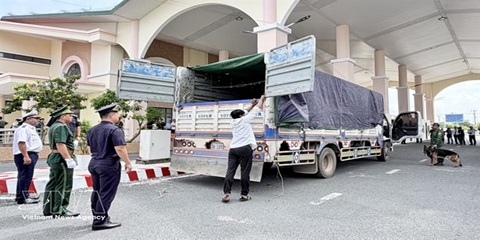
Trade between Việt Nam and Cambodia continues to grow, remaining a bright spot and a key pillar of bilateral cooperation as the two countries aim to raise two-way trade to US$20 billion in the coming years. After setting a record of more than $11.3 billion last year, bilateral trade reached about $8.7 billion in the first eight months of this year, up 8.3 per cent year on year.
VIETNAM ECONOMY INVESTMENT
FRUIT AND VEGETABLE EXPORTS POISED TO HIT $10 BILLION IN 2026
Fruit and vegetable exports are on track to reach nearly US$10 billion in 2026, after rising 19.9 per cent year on year to nearly US$7.4 billion in the first nine months, driven by strong seasonal demand and abundant tropical fruit supplies. The Ministry of Agriculture and Environment said the growth reflected stronger international demand for fresh produce and processed agricultural products.
Events Sponsors